
Millions of people fall victim to scams each year, suffering both financial losses and emotional harm. Victims often struggle with damaged self-confidence and difficulty trusting themselves and others. While the financial toll is measurable, often forcing people to scramble to replace money needed for basic living expenses, the emotional damage can be equally devastating. Some victims may withdraw from family and friends, overwhelmed by embarrassment, anger, anxiety and shaken confidence. However, there are actions for scam victims to take, such as notifying their financial institution, that may be critical to mitigating the impact of scams and preventing future losses.
Financial institutions serve as an important line of defense for scams, often identifying suspicious transactions that differ from customers’ typical payment patterns. They may also provide recommendations for scam victims to protect their accounts and find additional resources for support. The scenarios below, based on examples shared by financial institutions, illustrate how scam victims have navigated these challenges and found paths forward.
Scam tactic: Overdue property taxes and the urgency to pay
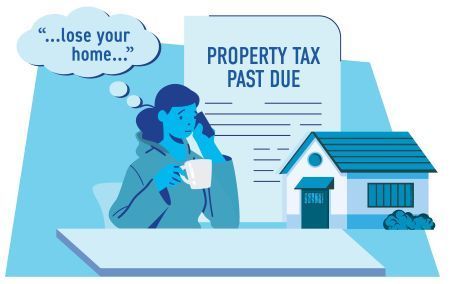
Martha receives a phone call from someone claiming to represent her mortgage company. The caller insists that her property taxes were severely past due and that she would lose her home without immediate payment.
Panicked, Martha writes down the instructions from the caller:
- Withdraw $12,075 from her bank immediately.
- Tell the bank teller the money is for home repairs.
- Do not mention the overdue taxes to anyone, including bank staff.
- Call the “mortgage company” back at the phone number they provided once she has the cash so they can arrange a pickup at her home.
At her local bank branch, her regular teller notices something is wrong, as Martha seems distracted and anxious. The teller attempts to strike up a conversation with Martha, but Martha insists she’ll be fine once she has her money. When the teller asks how she plans to use the money, Martha hesitates and doesn’t answer. Concerned that Martha might be ill or caught up in a scam, the teller consults her manager.
The branch manager gently asks Martha if everything is OK and whether someone is instructing her to withdraw the cash. Martha explains the urgent phone call about her overdue taxes. The manager immediately recognizes several red flags:
- Urgency to pay taxes to avoid the loss of Martha’s home.
- Cash withdrawal requirement rather than payment through established channels.
- Secret instructions when legitimate transactions require no deception.
- Home pickup arrangement for the cash payment, which no legitimate business or organization would request.
The branch manager asks Martha a crucial question: Had she verified the tax delinquency directly with the local tax authority? At that moment, Martha realizes she may have been the target of a scam.
Martha agrees to contact the tax office before proceeding. Living on a limited income, a loss of over $12,000 would have significantly impacted her financial security. The branch manager warns that the criminal would likely continue calling and advises her to avoid further contact. The manager also provides information for recognizing scam red flags and reporting scams.
Though grateful for the intervention, Martha feels deeply embarrassed. The branch manager reassures her that millions of people fall victim to scams because criminals use sophisticated deception and manipulation tactics.
When Martha calls her adult son to explain what happened, he offers to become more involved in her finances and reminds her that she can call him any time she needs help.
Scam tactic: Investment scams and the lure of higher returns
John is worried his retirement savings won’t last through his golden years. With retirement planned within five years, he needs investments with strong returns to meet his financial goals.
After researching options with well-known financial companies, John encounters what seems like a better opportunity on social media. Someone claiming to be a financial planner at an established firm advertises a new business investment with over 20% returns. The offer is time-sensitive — only initial investors can access this rate. The investment is described as virtually risk-free due to pending contracts with major corporations.
Believing this investment would secure his retirement, John authorizes a $10,000 payment from his bank account to the investment company. He watches his account balance grow online by over 20% as promised. John invests an additional $50,000 and is happy to see his investment increase each month.
After several months of closely tracking his investment, John is suddenly unable to access the investment website. He receives an error message — the link is no longer valid. Searching online, he discovers a news article revealing the entire operation is a scam with hundreds of potential victims. The article urges victims to contact local law enforcement.
John files a police report and reports the scam to the Internet Crime Complaint Center (IC3) (Off-site) and the Federal Trade Commission (FTC) (Off-site). He contacts his bank about the fraudulent payments but holds little hope of recovery. Soon after, he receives an email from a company claiming they could recover most of his money for a $5,000 upfront fee. Having learned about retargeting tactics used on scam victims, John immediately recognizes this as another scam.
The investment scam costs John $60,000. In hindsight, he realizes he had never independently verified the investment’s legitimacy. He had been deceived by the financial planner’s professional online profile and the legitimate company names referenced in the offer.
The financial loss derails John’s retirement plans. He also struggles with feelings of insecurity, anxiety and embarrassment. After a month, he shares his experience with family and friends and is surprised by their support. Talking with others in his community who had also lost money to scams encourages him — he wasn’t alone and his experience wasn’t unique. Confident he could learn from the experience and move forward, John decides to share his story publicly to raise awareness and potentially prevent others from becoming victims.
Seek support and leave blame behind
These scenarios represent victims who successfully moved past the financial and emotional impacts of scams. However, for many people, scams create significant hardships that affect their quality of life and living conditions. Tough financial decisions often become necessary to recover from such losses.
For scam victims, the path to overcoming the impact of a scam varies for each person. Leaning on family and friends for support and avoiding self-blame can be an important step. Many people never disclose or report that they were scammed, while others find purpose in sharing their survivor stories to help others avoid similar scams. Leveraging the available support and information provided by financial institutions and other organizations can help scam victims work through the impacts and protect themselves from future fraud.
Take the next step
The Federal Reserve provides the payments industry with educational resources to help financial institutions combat payments fraud through stronger identification and prevention.
- Visit our Scams Mitigation Toolkit (Off-site) for more information on how to identify and prevent other types of scams.
- Learn how the ScamClassifierSM (Off-site) model can provide your organization with consistent and detailed classification and identification of scams and related trends – helping promote accuracy of scam reporting, detection and mitigation.
- Check out these resources for more information about the scenarios explored in this article: