How Credit Union of Colorado built confidence in instant payments, one transaction at a time
10/26/2026
Instant payments are quickly becoming table stakes for digitally savvy consumers who expect their money to move fast. At Credit Union of Colorado (Off-site), where members are highly engaged in online and mobile banking, that expectation led to personalized digital experiences that includes easy access to instant payments, too.
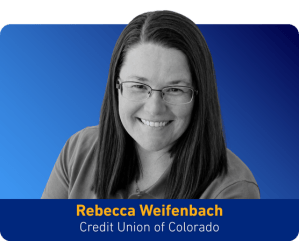
Rebecca Weifenbach, senior digital services analyst at Credit Union of Colorado, shares how the FedNow® Service is reshaping their digital member experiences and how the credit union implemented systems to support instant payments.
Q: How are your members using instant payments? And how are you delivering the option of an instant payment to them in a way that encourages them to use this capability?
A: “Our credit union started using the FedNow Service to only receive instant payments, meeting needs like payroll, gig work and tax refunds. We soon realized that sending payments instantly was equally valuable to our 160,000 members — if not more so. They expect fast money, whether sending funds to family and kids in college, or paying rent electronically. Many of our members get paid the same day their rent is due, so instant payments are a real help there.
“As soon as we added an ‘instant pay’ button to our digital banking platform, member behavior started to change. People would test the capability with small amounts, then move to larger ones once they saw the payments really did flow instantly. Feedback from both members and employees has been strong.
“Our digital banking platform makes the instant payment option clearly visible, though we haven’t marketed it heavily otherwise. Members can even switch to instant payment mid-transaction during a standard external transfer.”
Q: You put strong fraud safeguards in place before launching instant payments — how are these controls shaping your member experience? Has it helped your confidence about mitigating risk as your instant payment volumes grow?
A: “We started implementing fraud rules and dynamic limits about a year before we started our instant payment journey. For every payment, we have a system that looks at behavioral data, transaction history and destination details to determine whether additional authentication is needed. Trusted, long-standing members have greater flexibility than newer ones with less history. These safeguards have boosted confidence on both sides — for our management and our members.
“If a member is performing an instant payment transaction, we have a ‘brain’ behind it that looks at behavior data, transaction data and where the member’s money is being sent, which helps us determine if we need additional authentication information to verify the transaction. Members with a longer payment history have greater scope than newer members with whom we have less history. Fraud safeguards have boosted the confidence of both Credit Union of Colorado management and members about instant payments.”
Q: What advice do you have for other financial institutions that want to explore ways to enable instant payments for their customers or members?
A: “Go for it. It was a pretty seamless transition for us. The key was putting fraud controls in place beforehand and clarifying our strategy and risk appetite. Without that foundation, we wouldn’t have had the same success.”
Want to see how easy integrating instant payments can be? Talk to your Federal Reserve relationship manager for recommendations on personalized next steps. And read more interviews in our FedNow Q&A series.